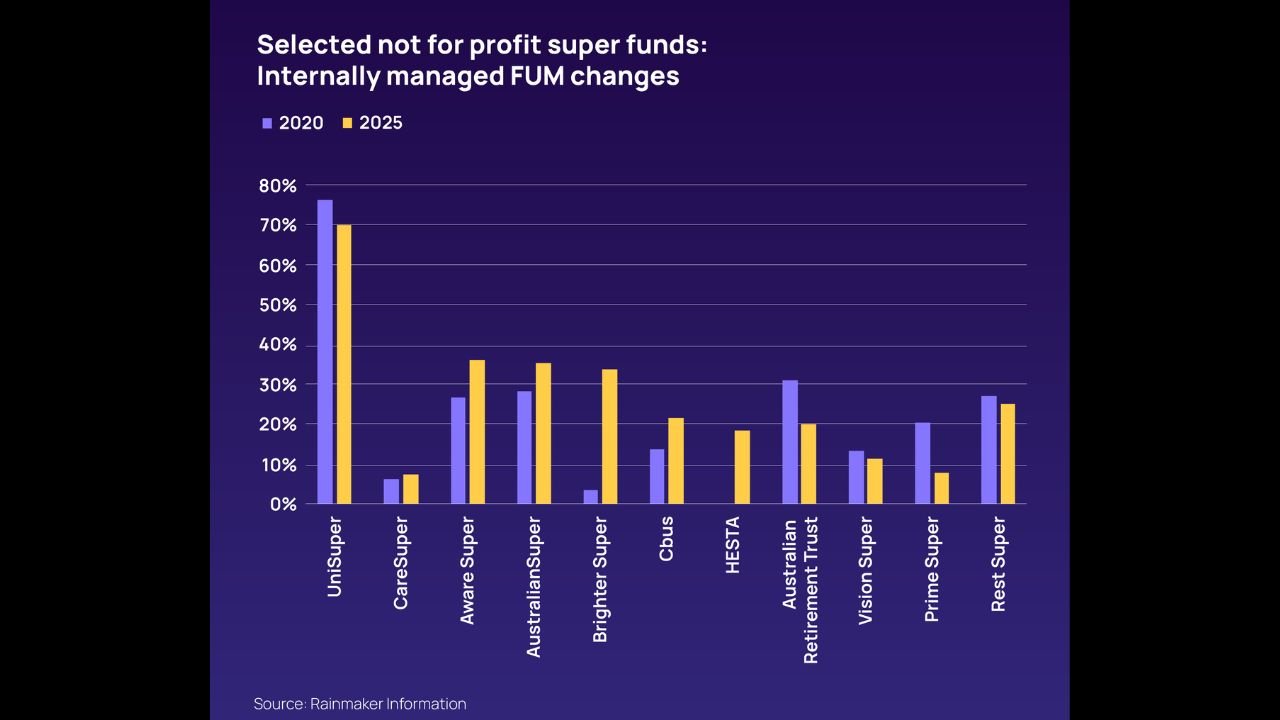
About one million Australians are exposed to superannuation funds described as unsustainable in October 2026 reporting based on APRA data, with the affected population rising roughly 35 per cent over the latest financial year. The figures have renewed concern about whether some funds can continue delivering competitive outcomes. However, sustainability concerns, poor investment performance and insolvency are different issues, and the headline should not be read as saying that one million people have lost their retirement savings.
What the Latest Report Says
The Australian Financial Review reported the increase on October 18, 2026. Its coverage said the number of people exposed to unsustainable funds had risen by more than 250,000 during the financial year.
Those numbers describe the scale of the reported concern. They do not, by themselves, identify every affected product, explain every trustee’s circumstances or quantify losses for individual members. A fund-level warning should therefore be read alongside the exact APRA measure and the reporting period behind it.
The increase of about 35 per cent is a change in the affected population, rather than an investment-return figure. It does not mean account balances fell by 35 per cent or that the entire superannuation industry has been classified as unsustainable.
What Does Unsustainable Mean in This Context?
Sustainability concerns relate to a fund’s ability to support competitive member outcomes over time. They can involve scale, membership trends, costs and the capacity to maintain effective operations. That is different from a simple statement that a fund’s assets have disappeared.
Investment performance is another dimension. A product can lag its benchmark even while the broader fund continues operating. Conversely, a good short-term return does not resolve every question about administration costs, governance or the long-term direction of membership.
The practical implication is that labels need context. The word unsustainable should not be used as a substitute for a formal finding of insolvency, fraud or an inability to pay benefits unless the evidence establishes that separate conclusion.
APRA’s 2026 Performance Test
APRA released its 2026 superannuation performance-test results on August 28. The annual test assesses products against prescribed measures rather than simply ranking funds by the return they achieved in a single year.
Twelve of 547 tested product offerings failed in 2026, compared with seven in 2025. The failures included 11 platform trustee-directed products and one MySuper product. Five platform products failed for at least two consecutive years.
Those counts refer to products, not twelve separate funds. A trustee can be responsible for more than one product, and a large fund can offer multiple investment choices. Keeping the unit of measurement clear is essential when interpreting the data.
What Happens When a Product Fails?
Members of a product that fails the legislated test must be notified in writing. Products that fail in two consecutive years must close to new members. These consequences are designed to place pressure on trustees to address persistent underperformance.
Closure to new members does not automatically mean an existing member’s account has been closed or that the member’s money is unavailable. The specific consequences depend on the product, the trustee’s response and the applicable rules.
For that reason, a general news headline should not replace a notice from the relevant fund. The notice identifies the actual product and explains the result that applies to its members.
The Broader Australian Superannuation Picture
APRA’s June 2026 statistics put total Australian superannuation assets at approximately $4.8 trillion, including about $3.4 trillion in APRA-regulated funds. Total contributions reached $236.3 billion over the year to June.
These figures show why a serious problem affecting some funds can coexist with growth across the system. Industry-wide asset growth does not establish that every product is competitive, while concerns about a subset do not mean the whole system is shrinking.
Which Data Can Be Compared?
APRA’s Comprehensive Product Performance Package combines the legislated test with broader information on returns, fees and costs. Its 2026 coverage includes 742 product offerings and approximately $1.8 trillion in accumulation member benefits.
The package has a different scope from the performance test alone. A reader should therefore check whether a figure refers to tested products, a broader set of offerings, member accounts or total assets. Mixing these categories can produce a misleading comparison even when each individual number is correct.
Quarterly product statistics and the annual superannuation bulletin provide additional detail on product structures, membership and financial measures. They are useful for understanding the basis of a report rather than relying solely on the headline.
Two Recent Related Social Media Posts
2026 results announcement — APRA on LinkedIn: The regulator highlighted its Comprehensive Product Performance Package, explaining that it combines performance-test outcomes with additional investment and fee measures. The post concerns the official data release.
Following the August 2026 release — True North Lifestyle on LinkedIn: A related post summarised the 547 tested offerings and 12 failures. It is commentary on the results, while APRA’s published material remains the source for the underlying figures.
What the Numbers Establish
The October report raises a significant sustainability concern, but it is not a finding that one million members have lost their super. Product performance, fees, fund sustainability and individual account outcomes need to be assessed separately. The exact product name, metric and reporting period are essential to understanding what any warning means.