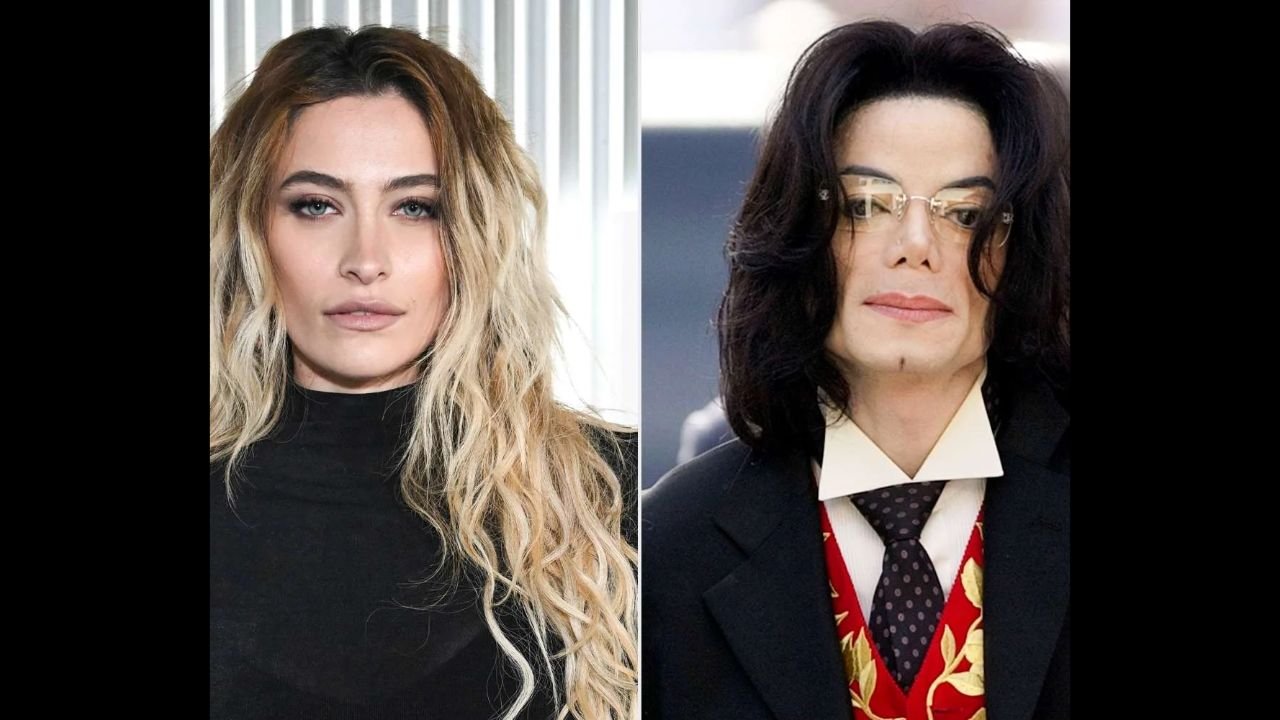
Paris Jackson, the 28-year-old daughter of Michael Jackson, has asked a Los Angeles court to order the transfer of $600 million from her late father’s estate into the Michael Jackson Family Trust. The November 2026 filing has intensified a dispute over how the singer’s fortune is managed, with Paris questioning the estate’s financial decisions and its failure to fully fund the trust established for Michael’s children.
The estate disputes her allegations, insisting that substantial money has already been distributed to the beneficiaries and that unresolved tax matters continue to complicate the transfer of assets.
$600 Million Demand
Paris Jackson is seeking a $600 million transfer into the family trust, rather than requesting that the entire amount be paid directly to her.
Her petition was filed in Los Angeles County Superior Court as part of the ongoing administration of Michael Jackson’s estate.
The request concerns money that Paris believes should already be held under the trust arrangements established by her father.
She argues that the prolonged delay has prevented the beneficiaries from receiving the financial independence intended under those arrangements.
The court must determine whether the requested transfer is legally appropriate.
Who Are the Beneficiaries?
Michael Jackson’s three children are central to the dispute.
They are Prince Jackson, 29; Paris Jackson, 28; and Bigi Jackson, 24, formerly known publicly as Blanket.
The siblings are beneficiaries of the family trust created as part of their father’s estate planning.
Michael Jackson died on June 25, 2009, leaving behind valuable music rights, business interests and other assets.
Since then, the estate has undergone major financial changes, including debt restructuring and substantial commercial transactions.
Paris’s latest petition raises questions about when those assets should move into the trust.
Why the Trust Matters
A family trust is a legal arrangement through which assets are managed for designated beneficiaries.
According to the reported terms of Michael Jackson’s trust, his children were expected to begin receiving income from their shares at age 21.
The arrangement also provides for distributions of principal at later milestones.
Those ages are 30, 35 and 40, allowing beneficiaries to receive increasing control over their inheritance as they grow older.
Paris argues that the estate’s continued administration of the money interferes with the intended structure.
The dispute therefore concerns control and timing, not simply the overall size of the family’s wealth.
Unfunded Trust Claim
One of the strongest allegations in Paris’s filing concerns the trust’s funding.
She claims the principal family trust remains unfunded 17 years after her father’s death, despite the estate’s substantial earnings.
Michael Jackson’s music and commercial interests have generated significant revenue through licensing, recordings and business transactions.
Paris argues that these financial gains should have allowed the estate to transfer substantial assets into the trust.
Her petition questions why beneficiaries continue relying on payments controlled by estate administrators.
However, the estate maintains that outstanding legal and tax obligations prevent the requested funding.
John Branca Dispute
John Branca, Michael Jackson’s longtime attorney and estate executor, is a central figure in the disagreement.
Paris alleges that Branca has maintained excessive control over the estate’s financial resources.
Her filing reportedly describes his management as an “iron grip” over the family’s money.
She argues that the beneficiaries should have greater control over assets intended for them.
These statements are allegations made in litigation, not findings of misconduct by a court.
The estate has defended its administration and rejected suggestions that the children have been improperly denied financial support.
Payment Allegations
Paris has also questioned payments allegedly made by estate administrators to professional associates.
Earlier disagreements involved what she described as non-contractual gifts or bonuses.
Her latest filing claims that after she challenged certain financial decisions, the estate responded with aggressive litigation.
She further alleges that the siblings’ financial allowances were reduced by millions.
The estate has rejected the claim that payments were withheld or reduced as retaliation, describing that allegation as a fabrication.
Whether any disputed payments were improper remains a matter for the courts.
Estate’s Response
Representatives for Michael Jackson’s estate strongly dispute Paris’s account.
The estate says more than $200 million has already been distributed for the benefit of Michael’s three children.
Its position is that the beneficiaries have received substantial financial support even though the principal trust has not been fully funded.
Estate representatives also argue that administrators have a legal responsibility to preserve sufficient assets for unresolved liabilities.
The disagreement highlights the difference between distributions made for beneficiaries and the formal transfer of estate assets into a trust.
Both sides are asking the court to accept different interpretations of the estate’s obligations.
IRS Tax Dispute
The estate identifies its longstanding dispute with the Internal Revenue Service as a major obstacle to completing trust funding.
Following Michael Jackson’s death, the IRS challenged valuations of certain estate assets.
The original tax and penalty demands reportedly approached $700 million.
Although the estate successfully contested substantial portions of those claims, administrators maintain that remaining tax issues must be resolved before final distributions can occur.
Their argument is that transferring too much money prematurely could leave the estate unable to meet outstanding obligations.
Paris disputes whether those concerns justify the continued delay.
Estate’s Wealth
Michael Jackson’s estate has generated substantial income since 2009.
Its assets include valuable music interests, licensing arrangements and proceeds from major commercial deals.
One significant transaction involved Sony acquiring an interest in Michael Jackson’s music assets.
Reports surrounding the latest dispute suggest the estate holds approximately $850 million in cash and cash-equivalent assets.
Paris’s lawyers argue that such resources strengthen the case for funding the family trust.
The estate, however, maintains that available cash cannot be considered independently of potential liabilities and continuing administration costs.
What Happens Next?
A court hearing is reportedly scheduled for December 4, 2026, in Los Angeles.
The proceedings are expected to address Paris’s request for trust funding and related concerns about estate administration.
The judge may consider financial records, outstanding obligations and the legal requirements governing distributions.
A hearing does not necessarily guarantee an immediate final ruling.
Additional evidence, arguments or proceedings could be required before the dispute is resolved.
Until then, the $600 million transfer remains a request rather than a completed transaction.
Latest Update
As of November 2026, Paris Jackson’s legal dispute with Michael Jackson’s estate remains unresolved.
She wants $600 million transferred into the family trust and greater accountability over financial decisions affecting the beneficiaries.
The estate maintains that the children have already received substantial benefits and that unresolved tax matters restrict further transfers.
The central question is whether Michael Jackson’s estate must now move a significant portion of its assets into the trust established for Prince, Paris and Bigi.
The December court proceedings could provide an important indication of how the family’s inheritance will be managed in the years ahead.